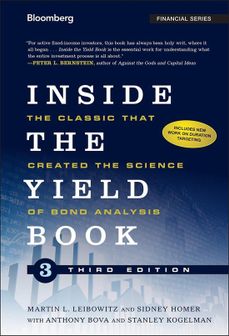
Inside Wiley-VCH GmbH Inside The Yield Book 3rd Hardcover

Inside Wiley-VCH GmbH Inside The Yield Book 3rd Hardcover

Alle 2 prijzen en aanbieders

Hot Deal Alert – Scherpste prijs!
Amazon.be· Bekende aanbieder
€ 51,46
-21% prijsdaling
3 tot 4 dagenGratis verzending
Check de website voor de levertijd | Gratis bezorgd > €20,-
Bekijk product
Bekijk product
Amazon.be Marketplace· Marketplace
€ 51,46
3 tot 4 dagenGratis verzending
Check de website voor de levertijd | Gratis bezorgd > €20,-
Bekijk product
Bekijk product

Specificaties

Overige kenmerken
Taal handleiding
en
Product lengte
23,1 cm
Product hoogte
3,6 cm
Product breedte
16 cm
Verpakking hoogte
23,7 cm
Verpakking lengte
3,4 cm
Verpakking breedte
16,2 cm
Verpakkingsgewicht
650 g
EAN
9781118390139

Productomschrijving

First published in 1972, and then updated in 2004, Inside the Yield Book is the widely-read classic volume that led to the modern science of bond analytics. With the global nature of today's investment management process and the increasing complexity of financial instruments, we may seem far removed from the bond markets that authors Martin Leibowitz and Sidney Homer first wrote about over forty years ago, but the ability of this new Third Edition to explain complex relationships in the debt markets in a logical and often intuitive way remains unchanged. Divided into three comprehensive parts, this new edition is filled with what many would consider some of the best information regarding bonds you'll ever find. It contains the complete original edition of Leibowitz and Homer's classic, which basically created the science of bond analysis through clear explanations of bond portfolio management and the math behind bond yields and prices. It also includes the 2004 updates to the classic, which developed a horizon-based approach to present-value and showed how these concepts could be generalized beyond bonds to become useful in the analysis of virtually any investment opportunity, including equities. While the earlier editions of this reliable guide focused on a single bond that was continuously held either to maturity or to some specified horizon, many bond investments take the form of portfolios composed of multiple bond holdings and a continually changing bond composition. A completely new part of this Third Edition contains material coauthored by Martin Leibowitz, Anthony Bova, and Stanley Kogelman that reflects this reality. It provides valuable insights into the often-surprising return behavior exhibited by Duration Targeting (DT) portfolios¿the most common form of bond management¿over multi-year horizons. Engaging and informative, this new part addresses some practical concerns in this arena as it: develops a trendline-based zero coupon bond model of Duration Targeting; explores the relationship between yield volatility and return volatility; moves beyond theory and simulated returns to the recorded returns of actual Duration Targeted portfolios; analyzes the so-called ''laddered portfolios'' that commonly are used by individual investors; and much more. Whether you're an institutional or individual investor, trader, or analyst, if you're looking to enhance your bond analysis skills, this authoritative work covers essential concepts and contains illustrative examples that will allow you to excel in today's challenging bond markets.

Reviews

Er zijn nog geen reviews geschreven

Heb jij dit product in bezit en wil je graag je mening geven? Start dan hieronder met het schrijven van je review. Afhankelijk van de details duurt het schrijven van een review gemiddeld tussen de 3 en 10 minuten. Met jouw mening help je andere bezoekers een betere keuze te maken én maak je iedere maand kans op €250,-! Klik hier voor de actievoorwaarden.

Welk cijfer geef jij dit product?