Choix le plus populaire – Meilleur prix !
Amazon.be· Vendeur reconnu
€ 154,36
6 jours ou plusLivraison gratuite
Check de website voor de levertijd | Gratis bezorgd > €20,-


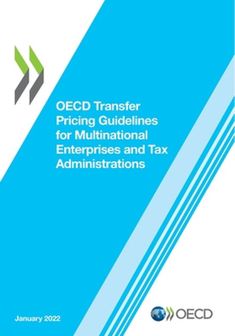
In a global economy where multinational enterprises (MNEs) play a prominent role, governments need to ensure that the taxable profits of MNEs are not artificially shifted out of their jurisdiction and that the tax base reported by MNEs in their country reflects the economic activity undertaken therein. For taxpayers, it is essential to limit the risks of economic double taxation. The OECD Transfer Pricing Guidelines provide guidance on the application of the arms length principle, which is the international consensus on the valuation of cross-border transactions between associated enterprises.
This January 2022 edition includes the revised guidance on the application of the transactional profit method and the guidance for tax administrations on the application of the approach to hard-to-value intangibles agreed in 2018, as well as the new transfer pricing guidance on financial transactions approved in 2020. Finally, consistency changes have been made to the rest of the OECD Transfer Pricing Guidelines. The OECD Transfer Pricing Guidelines were approved by the OECD Council in their original version in 1995.
Tu possèdes ce produit et tu aimerais donner ton avis ? Commence ci-dessous à écrire ton avis. Selon le niveau de détail, écrire un avis prend en moyenne entre 3 et 10 minutes. Avec ton opinion, tu aides les autres visiteurs à faire un meilleur choix et tu tentes chaque mois de gagner 250 € ! Clique ici pour les conditions de l’action.
