
Choix le plus populaire – Meilleur prix !
Amazon.be· Vendeur reconnu
€ 185,81
3 à 4 joursVerz. € 5,54
Check de website voor de levertijd | Gratis bezorgd > €20,-


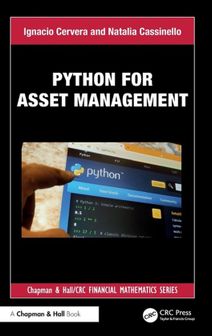
The book empowers non-programmers—portfolio managers, risk analysts, and students—to implement advanced models themselves. It responds to the growing demand for quantitative literacy in finance, especially in sustainable investing and smart beta strategies, areas of active research for both of the authors.
The asset management industry is undergoing a paradigm shift toward automation, transparency, and data-driven decision-making. Traditional tools (Excel, Bloomberg) are being replaced by programmable, scalable solutions. Yet most finance professionals lack accessible, practical training in applying Python to real portfolio problems.
Python for Asset Management fills that gap. The book empowers non-programmers – portfolio managers, risk analysts, and students – to implement advanced models themselves. It responds to the growing demand for quantitative literacy in finance, especially in sustainable investing and smart beta strategies, areas of active research for both of the authors.
Tu possèdes ce produit et tu aimerais donner ton avis ? Commence ci-dessous à écrire ton avis. Selon le niveau de détail, écrire un avis prend en moyenne entre 3 et 10 minutes. Avec ton opinion, tu aides les autres visiteurs à faire un meilleur choix et tu tentes chaque mois de gagner 250 € ! Clique ici pour les conditions de l’action.
