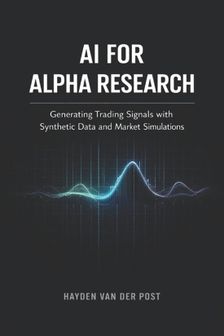
AI Libri GmbH AI for Alpha Research: Generating Trading Signals with Synthetic Data and Market Simulations: A Comprehensive Guide

AI Libri GmbH AI for Alpha Research: Generating Trading Signals with Synthetic Data and Market Simulations: A Comprehensive Guide

Tous les 1 prix et vendeurs

Hot Deal Alert – Meilleur prix !
Amazon.be· Vendeur reconnu
€ 26,56
3 à 4 joursLivraison gratuite
Check de website voor de levertijd | Gratis bezorgd > €20,-
Voir le produit
Voir le produit

Spécifications

Overige kenmerken
Product lengte
22,9 cm
Taal handleiding
en
Product hoogte
2,7 cm
Verpakking hoogte
2,7 cm
Verpakking lengte
22,9 cm
Verpakkingsgewicht
508 g
Verpakking breedte
15,2 cm
Product breedte
15,2 cm
EAN
9798246315705

Description du produit

Reactive PublishingWhat if you could stress test your trading ideas across thousands of alternate market realities before risking a single dollar?AI for Alpha Research is a practitioner's guide to designing, validating, and scaling trading signals using synthetic data generation and high-fidelity market simulations. Built for quants, discretionary traders, and financial engineers, this book shows how to move beyond historical backtests into probabilistic scenario modeling that exposes hidden fragilities, regime dependencies, and nonlinear risk.Instead of relying solely on past data that may never repeat, you will learn how to construct simulated market environments that capture volatility clustering, structural breaks, liquidity shocks, and behavioral anomalies. By combining machine learning, stochastic modeling, and agent-based simulation, you will develop a more resilient framework for discovering alpha that survives real-world uncertainty.This book bridges theory and execution, guiding readers through signal design, feature engineering, synthetic dataset construction, and performance validation under adversarial conditions. You will learn how to reduce overfitting, quantify edge durability, and build adaptive strategies that evolve with changing market regimes.Inside, you will discover how to: - Generate synthetic financial time series that preserve statistical properties of real markets
- Use Monte Carlo simulations to test signal robustness across multiple futures
- Apply AI models to uncover nonlinear relationships traditional methods miss
- Stress test strategies against regime shifts, liquidity gaps, and volatility shocks
- Build research pipelines that integrate simulation, optimization, and live deployment
- Measure signal decay and edge persistence before capital allocationWhether you are developing systematic strategies, enhancing discretionary trading, or building institutional-grade research infrastructure, this book provides a blueprint for modern alpha discovery in an increasingly complex market landscape.AI for Alpha Research is for readers who want to move beyond hindsight bias and build trading systems designed for the markets of tomorrow, not the markets of the past.

Avis

Aucun avis n’a encore été écrit

Tu possèdes ce produit et tu aimerais donner ton avis ? Commence ci-dessous à écrire ton avis. Selon le niveau de détail, écrire un avis prend en moyenne entre 3 et 10 minutes. Avec ton opinion, tu aides les autres visiteurs à faire un meilleur choix et tu tentes chaque mois de gagner 250 € ! Clique ici pour les conditions de l’action.

Quelle note donnes-tu à ce produit ?